
Compare Us to Other Lenders
Healthcare practice owners often find that banks move too slowly and generic lenders offer the wrong funding structure. Here’s how we compare on the factors that matter most to your practice.
| What matters to you | National Business Capital | Traditional banks and SBA lenders |
|---|---|---|
| Covering the insurance payment gap | We provide a revolving Line of Credit you draw from on demand. Capital arrives within 24 to 48 hours of approval | Most offer fixed-term loans with set repayment schedules. Your payment timeline doesn’t adjust when insurance payments are late |
| Credit score requirements | We review your full revenue picture with no minimum FICO required. (Note: Credit profile may affect available terms and options.) | Many require 680 or higher. Many profitable, established practices get declined on that basis alone |
| Speed to capital | We fund within 24 to 48 hours of approval | Can take weeks to months to review and approve |
| What you pay interest on | You pay interest only on what you draw. The rest of your credit limit stays available at no cost | Many charge interest on the full loan balance from day one, whether you’ve used the capital or not |
| How your file gets reviewed | A dedicated advisor evaluates your practice goals and builds a funding recommendation around them | An automated system processes your file. They assign no advisor, and the system makes no adjustment for how healthcare revenue actually flows |
| Documentation required | 6 months of bank statements and basic business documents | 2 to 3 years of tax returns and detailed financial statements |

How it works
Get Funded in 4 Easy Steps
From the first conversation to funded capital, a dedicated advisor stays with you at every step.
- 1
Apply in minutes
Submit a short online application. We ask only for what we need to start your review.
- 2
Talk with your advisor
A dedicated advisor contacts you to understand your practice and what you need capital to accomplish. This is a real conversation with someone who understands how your practice earns and where it’s heading.
- 3
Review your options
Your advisor presents the Line of Credit structure that fits your timeline and intended use of funds.
- 4
Receive your funds
Once you confirm your selection, funds reach your account within 24 to 48 hours. Draw from your line as your practice needs capital, and the credit replenishes as you repay.
What Sets National Business Capital Apart
We evaluate more than your credit score. Our advisors look at how your revenue flows and what capital you need to accomplish. Then they recommend the structure that fits where your practice is heading.
As a direct lender that also works closely with capital providers across industries, we offer the speed and control of lending from our own balance sheet, plus the flexibility to tailor solutions when the situation calls for it.
| Quick Facts | |
|---|---|
| Funding Range | $250K to $15M |
| Time to Fund | 24 to 48 hours |
| Minimum FICO score | None Required |
| Cost Structure | Interest Only on What You Draw |
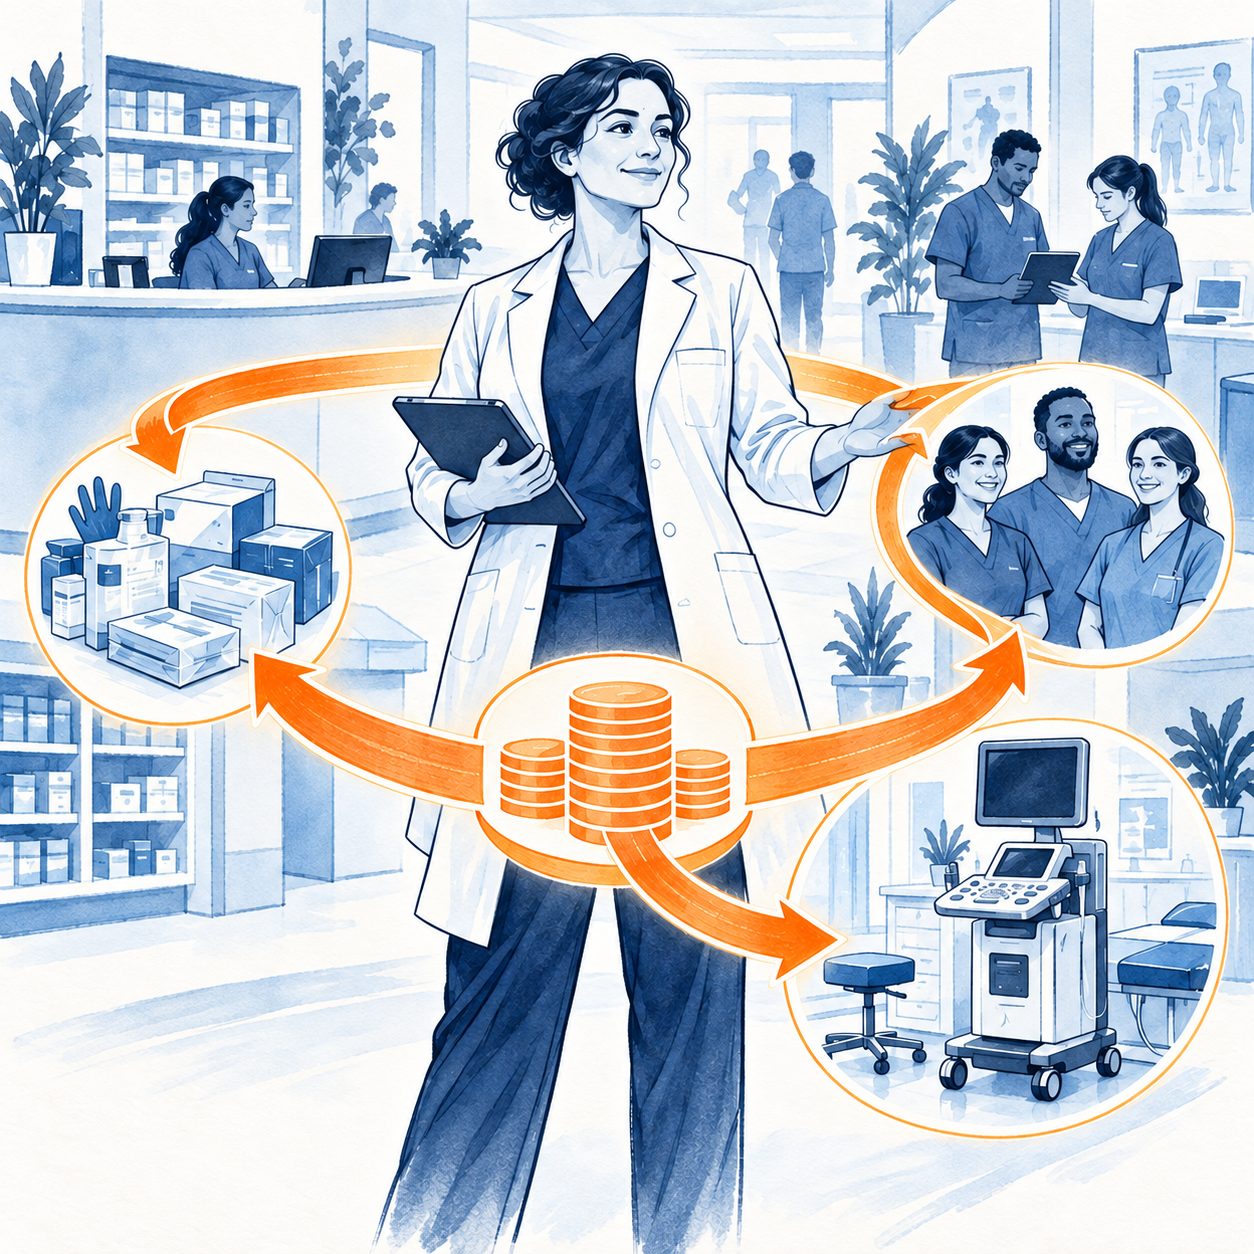
A Line of Credit gives your practice a funding tool you can draw from at any point in the billing cycle.
Pay your clinical and support staff on schedule, regardless of when claims arrive
Purchase diagnostic tools or new devices without pulling from operating reserves
Fund your expansion before new patient revenue builds to capacity
Keep operations funded when patient volume dips, without disrupting care delivery
Bring a specialist or key hire on before their revenue contribution comes in
Frequently Asked Questions
We fund established healthcare practices, from physician groups and specialty clinics to home healthcare companies and surgical centers. Eligibility varies by business profile. Talk to an advisor to find out where your practice stands.
Yes. That’s one of the most common reasons healthcare providers choose a Line of Credit over a Term Loan. You draw when claims are processing and repay once reimbursements arrive.
No. Our initial review uses a soft credit pull, which does not impact your score.
A Term Loan delivers a lump sum on a fixed repayment schedule. A Line of Credit stays available on a revolving basis. You draw what you need, repay it, and the credit opens back up. For healthcare practices managing unpredictable reimbursement timing, that flexibility fits the business model better.
Yes. Our advisors build long-term funding relationships, not one-time transactions. As your revenue grows and your goals change, we evaluate the structures that best support where your practice is heading next.
Our advisors understand that healthcare revenue moves on the insurance company’s schedule, not yours. We build funding around that reality. Talk to an advisor at National Business Capital to explore your options for a healthcare line of credit.