
Why Equipment Purchases Need Their Own Funding Approach
Most lenders evaluate equipment purchases like any other loan, based on a credit pull and last year’s revenue. That approach how long the equipment will earn revenue and how quickly you need it in service. A 5-year loan on equipment with a 15-year working life leaves you paying for it years after it stops earning money. A financing process that takes three weeks does not help when an auction closes Friday.
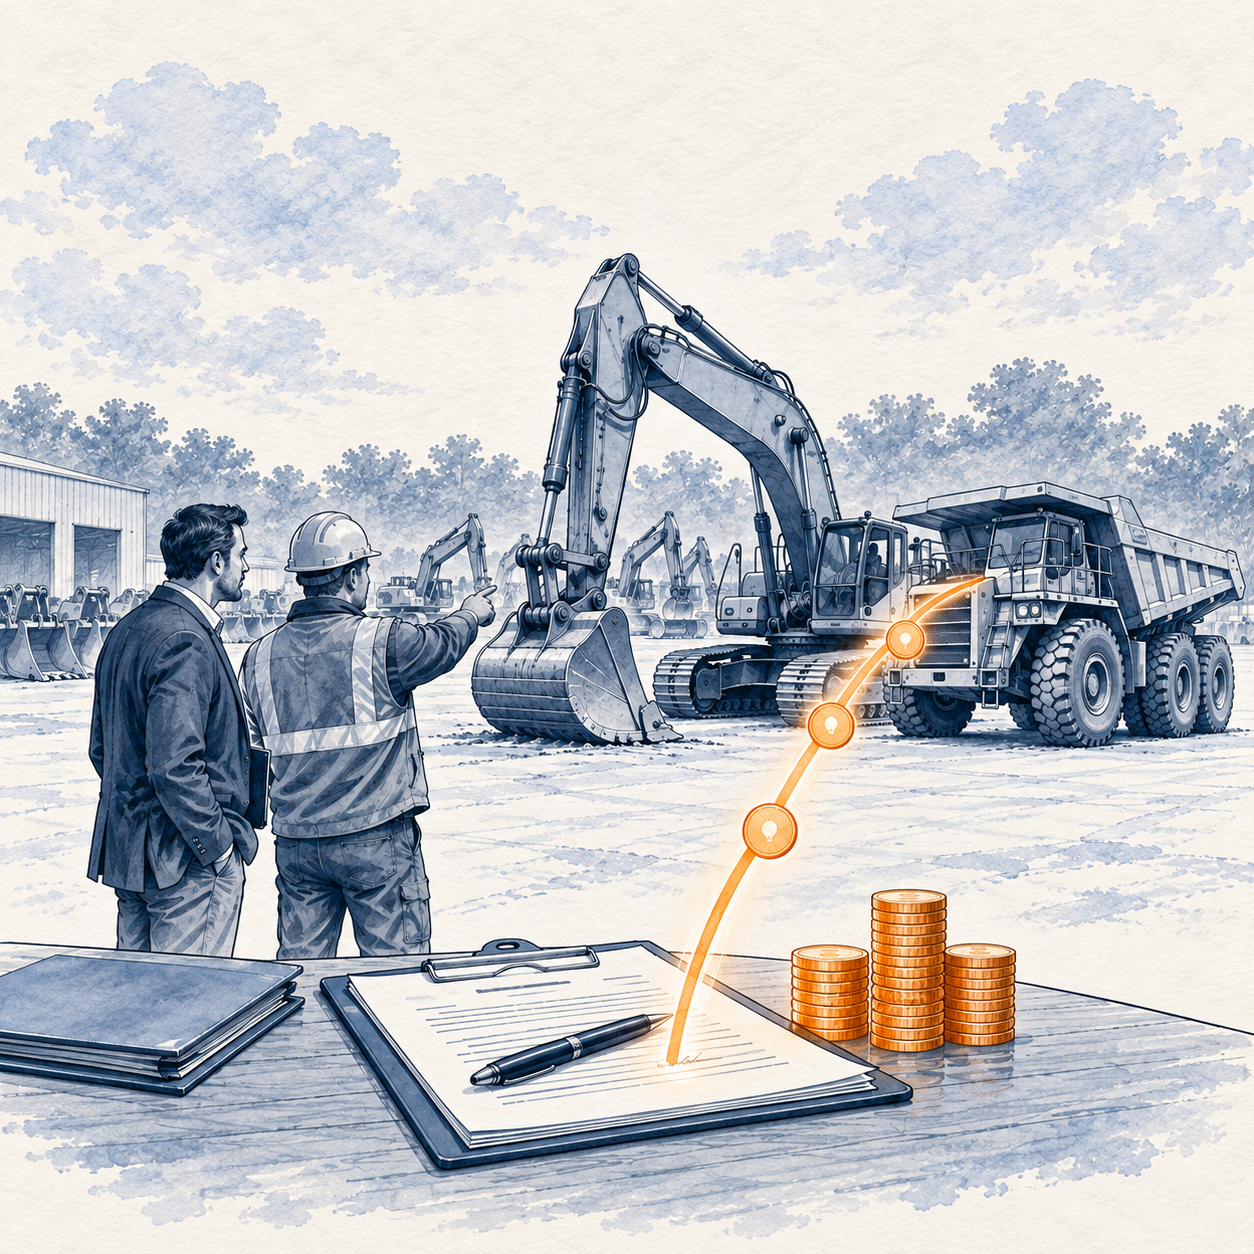
National starts with the equipment. Your advisor looks at what you are buying and when you need it, then recommends a financing option that fits.
Finance Your Next PurchaseMatching Your Situation to a Funding Structure
The right structure depends on what you are financing and how soon you need it in place. The table below maps common equipment situations to the structures that tend to fit best.
A National advisor confirms the right structure after reviewing your equipment and timeline.
| Situation | Best-fit structure | Why It Fits |
|---|---|---|
| Equipment fails on the job | Term Loan | Fast funds, term matched to the equipment's earning life |
| Buying equipment at auction or through a dealer | Term Loan or Cash Flow Financing | Moves fast enough to meet a fixed deadline |
| Adding equipment for a new or larger contract | Term Loan | Ties repayment to the job generating the revenue |
| Adding capacity ahead of a seasonal jump | Line of Credit | Keeps funds ready before the exact purchase date |
What to Know Before You Apply
Here is how National makes the financing process easier.
Financing a purchase usually doesn't put other assets on the line.
Most products require no collateral, and your advisor confirms which ones fit.
National is a direct lender.
We lend from our own balance sheet and work with capital providers across industries. That gives you direct control over the lending process.
Your advisor helps you compare offers.
Once National receives your application, your advisor reviews the available options with you so you can choose the one that fits your business.

How it works
How National Structures Equipment Financing
Here’s how we structure financing for businesses:
- 1
We start with the equipment
Your advisor looks at the type of machine and what you need it for.
- 2
We match the financing to the equipment
Your advisor weighs the equipment’s expected working life against your purchase timeline. They then recommend a Term Loan, Cash Flow Financing, or another option that fits.
- 3
We check the payment against your business
National reviews how your payment fits your existing revenue before you commit. This means the equipment adds value without straining your business.
- 4
We fund at the right pace
Eligible accounts can receive funds in hours. Most applications resolve within three business days once your documents are ready.
Here are some of the reasons businesses work with National.
When a forklift stops running mid-shift, work grinds to a halt. A Term Loan or dedicated equipment financing can get you a replacement fast.
Used equipment can sell fast when an auction is closing or a dealer has limited inventory. Financing arranged ahead of time lets you buy when the right machine comes up.
Winning a larger job sometimes means adding a machine instead of pushing your existing equipment harder. Financing the purchase lets you add the equipment you need.
Businesses with seasonal demand often need extra equipment before the busy season starts. Financing early means the equipment is ready when the work arrives.
How One Contractor Used Equipment Financing to Seize an Opportunity
A contractor found an opportunity to buy equipment from a competitor that was closing down. The business needed funding quickly, so National Business Capital helped the contractor secure an $850,000 term loan in three days. The financing let the contractor buy the equipment without using cash needed to run the business.
The new equipment helped the contractor work more efficiently and take on larger jobs, including government contracts. The business projected 200% revenue growth within one year.
Best Practices for Financing Heavy Equipment
Here are a few things to consider before you finance equipment.
Size the Term to the Equipment’s Working Life
A loan that outlasts equipment leaves you paying for a machine you no longer use. Match the term to how long the equipment will earn revenue so the payments stay tied to its useful life.
Keep Equipment Funding Separate From Operating Credit
A dedicated structure keeps a slow month from competing with a payment on equipment that is already earning.
Consider Resale Value
Heavy equipment holds value differently from other business assets. Think about the equipment’s expected resale value when deciding how much to finance.
Frequently Asked Questions
Most of National’s products carry no minimum FICO score. National considers your revenue and the strength of the financing request rather than relying on a set credit threshold.
National funds equipment-dependent businesses well beyond construction. Your advisor considers the equipment and your business when recommending a financing structure.
National finances a wide range of business equipment, from heavy machinery to more specialized equipment. We can review the equipment you need and help you choose the financing options that work for you.
Yes. Businesses can use equipment financing for multiple purchases, whether they need several machines for one project or want to add equipment over time.
Equipment purchases do not always line up with when cash becomes available. Standard loan programs may not account for how the equipment will generate revenue. National assigns an advisor to your purchase from the start to help you choose a financing structure that fits the equipment. With more than $3 billion funded since 2007, National offers up to $15 million in financing.
Ready to finance your next piece of equipment?